Credit Card Processing Fees: What They Are and Why They Matter
Credit card processing fees are the costs businesses pay each time a customer uses a credit or debit card. These fees may seem small on a per-transaction basis, but they can add up quickly and have a meaningful impact on profit margins. For small businesses, online stores, and subscription-based companies, understanding how these fees work is essential for pricing, budgeting, and choosing the right payment processor.
When a customer pays with a card, several parties are involved in moving money securely from the customer’s bank to the business’s bank account. Each party takes a cut, and together those charges make up the total processing cost. While fees can vary by provider, card type, industry, and transaction method, most businesses will encounter a similar set of fee categories.
How Credit Card Processing Works
Before breaking down the fees, it helps to understand the basic payment flow. When a card is swiped, tapped, inserted, or entered online, the payment processor sends the transaction details to the card network and then to the customer’s bank for approval. If the transaction is approved, the processor finalizes the payment and deposits the funds into the merchant account, usually within one to a few business days.
That process involves multiple service providers, which is why processing payments is not free. Each step includes a service charge for handling authorization, security, settlement, and risk management. The business pays these charges either directly or indirectly through the pricing model offered by the processor.
Common Types of Credit Card Processing Fees
Not all processing fees are the same. Some are charged by the card networks, some by the issuing banks, and some by the payment processor itself. Here are the most common fees businesses should know about.
Interchange Fees
Interchange fees are paid to the customer’s bank, also known as the issuing bank. These fees typically make up the largest portion of processing costs. The exact amount depends on several factors, including the card type, transaction method, business category, and whether the card was present at the time of sale.
For example, a rewards credit card may have a higher interchange fee than a basic debit card. A card-present transaction at a retail store may cost less than an online transaction, because card-not-present payments carry more fraud risk. Interchange fees are usually set by the card networks and are not negotiable for most businesses.
Assessment Fees
Assessment fees are charged by the major card networks, such as Visa or Mastercard. These fees are generally smaller than interchange fees and are based on a percentage of transaction volume. Although they are usually consistent across processors, they still contribute to the overall cost of accepting cards.
Assessment fees help support the infrastructure and operation of the card networks. Businesses may not always see them listed separately, but they are usually included in the total processing rate.
Payment Processor Fees
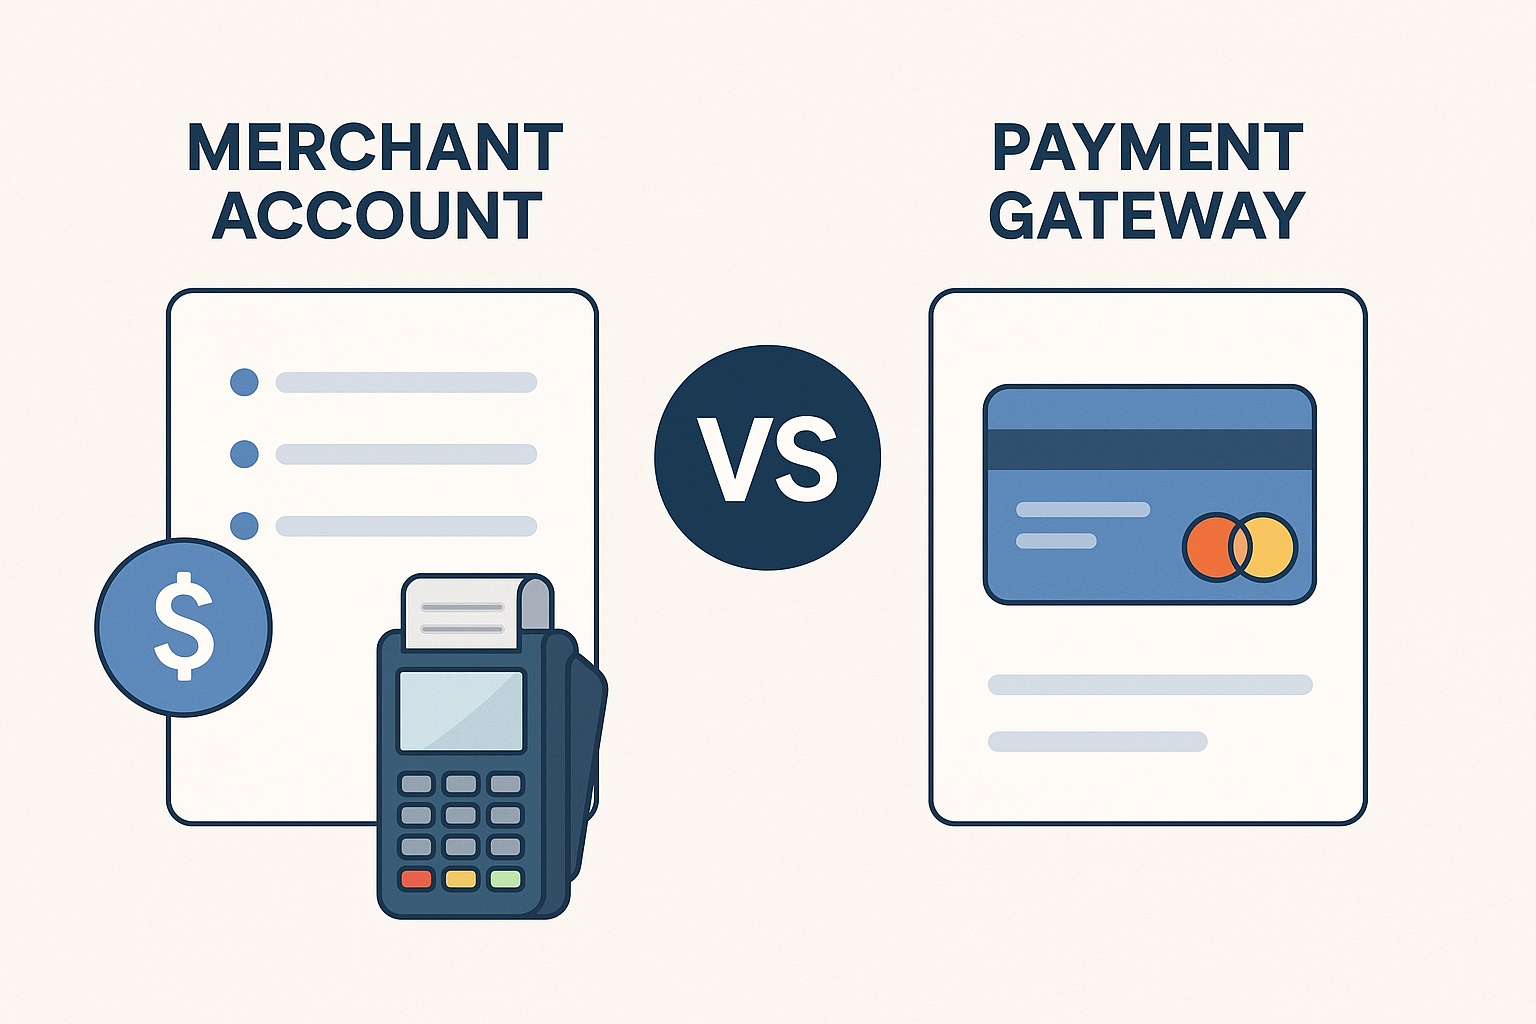
Payment processor fees are charged by the company that provides the merchant service. This provider handles the technical side of the transaction, routes payment information, and ensures the business gets paid. Processor fees may appear as a percentage of the transaction, a flat fee per transaction, or a combination of both.
Unlike interchange and assessment fees, processor fees can sometimes be negotiated, especially for businesses with strong sales volume. The pricing model a processor uses can have a major effect on total costs.
Monthly and Account Fees
Some processors charge monthly account fees in addition to per-transaction charges. These may include statement fees, gateway fees, PCI compliance fees, and customer support fees. While each fee may seem modest, the total can become significant over time.
Businesses should read the contract carefully to understand whether these fees are required, optional, or bundled into a broader service package.
Chargeback Fees
A chargeback happens when a customer disputes a transaction with their card issuer. If the dispute is resolved in the customer’s favor, the business may lose the sale and also pay a chargeback fee. These fees help cover the administrative cost of handling the dispute.
Chargebacks can be especially costly because they may also lead to higher processing rates or account restrictions if they happen too often. Reducing fraud, providing clear billing descriptors, and keeping accurate records can help lower chargeback risk.
Early Termination and Miscellaneous Fees
Some merchant agreements include early termination fees if a business cancels before the contract ends. Others may charge setup fees, batch fees, or equipment rental fees. These charges are not always part of every plan, but they can significantly affect the true cost of accepting cards.
It is important to review the full contract and ask for a clear list of all possible fees before signing an agreement.
Common Pricing Models for Processing Fees
Processors use different pricing models to package these fees. Understanding these models can help businesses compare offers more accurately.
Flat-Rate Pricing
With flat-rate pricing, the processor charges the same rate for most transactions, such as 2.9% plus $0.30. This model is simple and predictable, making it popular with small businesses and startups. However, it may be more expensive for businesses that process a high volume of transactions or have many low-risk payments.
Interchange-Plus Pricing
Interchange-plus pricing separates the interchange and assessment fees from the processor’s markup. This model is often considered the most transparent because businesses can see the actual cost of each transaction plus the provider’s added fee. It can be more cost-effective for many businesses, especially those with higher sales volume.
Tiered Pricing
Tiered pricing groups transactions into categories such as qualified, mid-qualified, and non-qualified. Each tier has a different rate, but the criteria for each tier are not always clear. This structure can make it harder to predict costs and may result in higher fees for some transactions.
Membership or Subscription Pricing
Some processors charge a monthly membership fee and pass through interchange at a lower markup. This model may benefit larger businesses or those with steady volume, but it works best when the business understands how the monthly fee compares with per-transaction savings.
What Affects Credit Card Processing Fees?
Several factors influence how much a business pays to accept cards. The type of card is one of the biggest drivers. Rewards cards, corporate cards, and premium cards often cost more than standard debit cards. The transaction method also matters: card-present sales are generally less risky than card-not-present sales, so online and keyed-in transactions usually cost more.
Business type can affect rates as well. Some industries are considered higher risk because of chargeback rates, fraud exposure, or regulatory issues. Transaction size and monthly volume also matter. Businesses with larger processing volumes may qualify for better pricing or lower markups.
Finally, processor choice makes a difference. Some providers offer transparent pricing with fewer hidden fees, while others rely on bundled pricing that may be harder to compare. Shopping around can uncover meaningful savings.
How Businesses Can Reduce Processing Fees
Although businesses cannot eliminate processing fees entirely, they can take steps to manage them more effectively. One of the easiest ways is to choose the right pricing model based on sales volume and transaction patterns. A small business with occasional sales may prefer flat-rate pricing, while a growing company may save more with interchange-plus pricing.
Encouraging debit card payments can also lower costs, since debit transactions often carry lower interchange fees. For online businesses, improving fraud prevention tools can reduce chargebacks and associated costs. Clear billing descriptions, prompt customer service, and strong refund policies may also help prevent disputes.
Businesses should regularly review statements to spot unnecessary fees or rate increases. Comparing multiple providers once a year can reveal better options, especially if the business has grown since first signing up.
Why Understanding Fees Matters
Credit card processing fees affect more than just accounting. They influence pricing strategy, customer payment options, cash flow, and profitability. A business that understands its fees can make smarter decisions about which processor to use, how to price products, and whether certain payment methods are worth encouraging or discouraging.
Even a small reduction in processing costs can lead to meaningful savings over time. For businesses with high transaction volume, better fee management can free up money for marketing, hiring, inventory, or expansion.
Conclusion
Credit card processing fees are a normal part of doing business, but they do not have to be confusing or overwhelming. By understanding the different types of fees, how pricing models work, and what factors drive costs, businesses can choose payment solutions more confidently. The key is to compare providers carefully, read the fine print, and stay proactive about managing payment costs.