What Is Tiered Pricing in Merchant Services?
Tiered pricing is a payment processing model that groups card transactions into different pricing categories, or “tiers,” rather than charging one flat interchange-plus rate for every transaction. In a tiered setup, your merchant services provider assigns each sale to a tier based on factors such as card type, risk level, transaction method, and whether the card was present.
This pricing structure is common in merchant services because it gives processors flexibility in how they price transactions. Instead of passing through the exact interchange fee and adding a transparent markup, the provider bundles costs into tiers. The result can be simple to explain on the surface, but it is often harder for merchants to predict the true cost of acceptance.
How Tiered Pricing Works
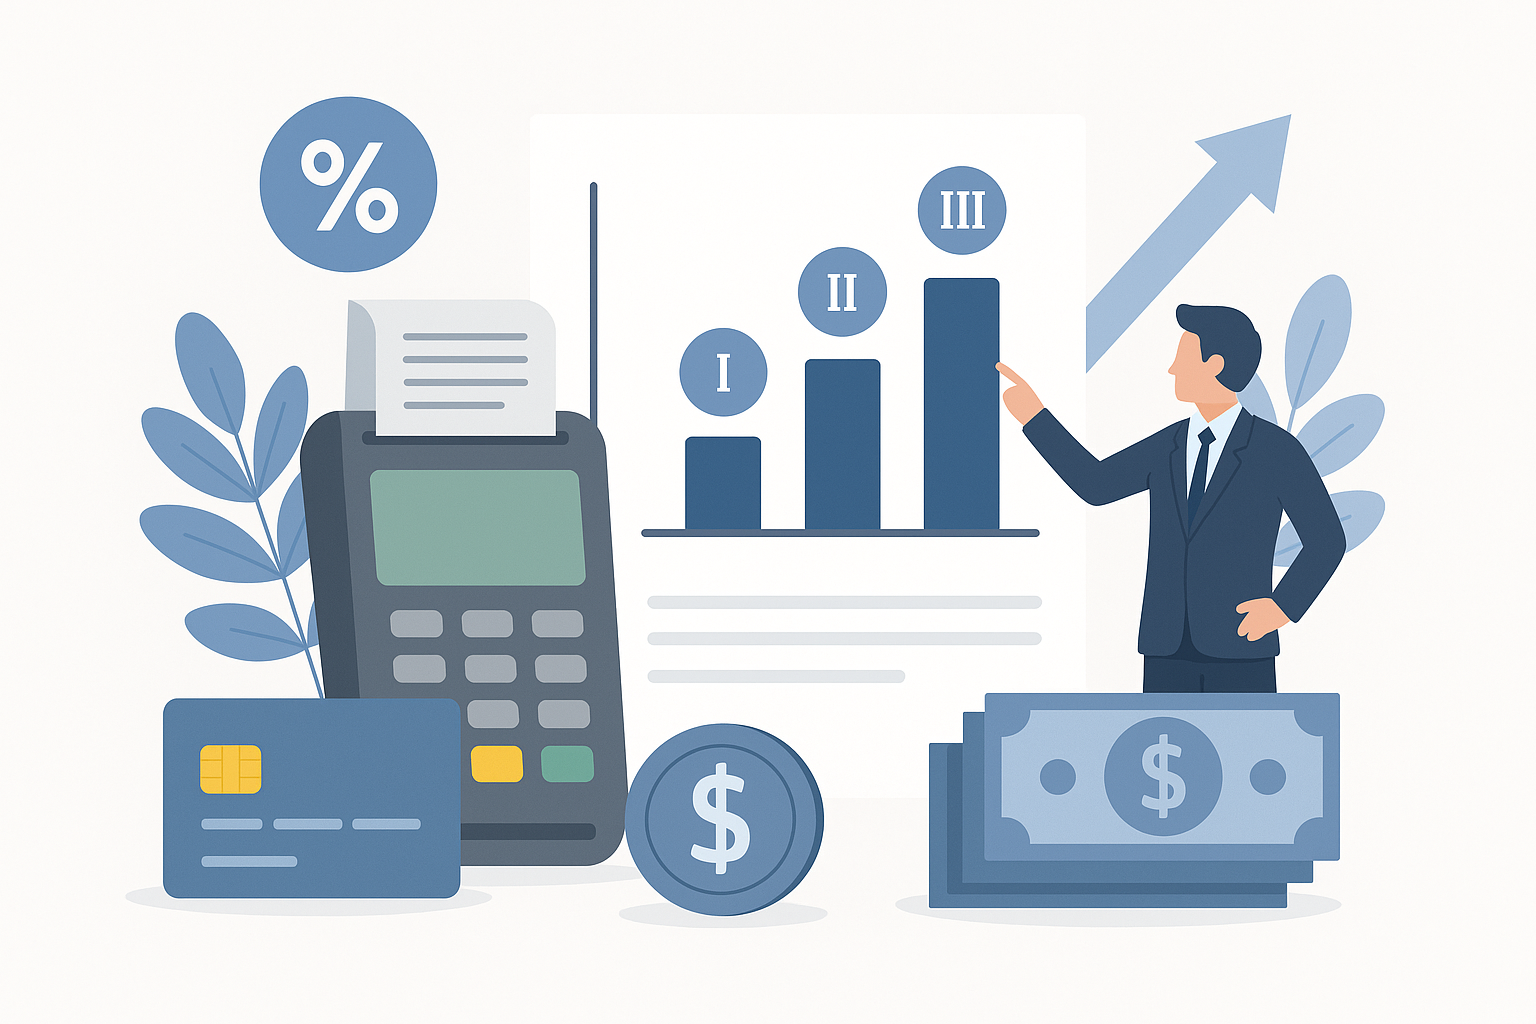
Most tiered pricing models divide transactions into three main categories:
Qualified
Qualified transactions are typically the lowest-cost tier. These are usually standard debit or credit card payments that meet the processor’s preferred criteria, such as being swiped in person with no extra risk factors.
Mid-Qualified
Mid-qualified transactions cost more than qualified ones. These may include cards that are keyed in, certain rewards cards, or transactions that do not meet every condition for the lowest tier.
Non-Qualified
Non-qualified transactions are usually the highest-cost tier. They can include premium rewards cards, corporate cards, international cards, or transactions that carry more fraud risk or processing complexity.
The challenge is that merchants often do not always know in advance which tier a transaction will fall into. A sale that looks ordinary may still be charged at a higher tier depending on the card brand, card type, or how the transaction is processed.
Why Processors Use Tiered Pricing
Processors use tiered pricing because it allows them to package multiple costs into a simplified rate structure. It can also help them protect margins by assigning higher fees to transactions that are more expensive or riskier to process.
For merchants, tiered pricing may seem attractive at first because the advertised rates can look low. However, the lowest tier only applies to a portion of transactions, and the final monthly cost may be much higher than expected if many payments fall into mid-qualified or non-qualified categories.
Pros of Tiered Pricing Merchant Services
Tiered pricing is not always the wrong fit. For some businesses, it offers a few practical advantages:
- Easy to understand at a glance: Merchants can quickly see the basic structure of the pricing model.
- Potentially low advertised rates: The qualified tier may look competitive in sales materials.
- Simple statements: Some providers present fewer line items than interchange-plus billing.
- Suitable for low-risk businesses: Businesses with mostly card-present debit or standard credit transactions may see more sales qualify for the lowest tier.
That said, simplicity in marketing does not always translate to simplicity in real-world costs.
Cons of Tiered Pricing Merchant Services
The biggest drawback of tiered pricing is lack of transparency. Merchants often cannot easily determine why a transaction was placed into a certain tier, which makes it harder to verify charges or compare providers accurately.
- Less predictable pricing: Your rate can vary widely from one transaction to the next.
- Higher effective costs: Many businesses end up paying more than the advertised “qualified” rate suggests.
- Harder to audit: It can be difficult to tell whether a transaction was fairly categorized.
- Limited control: Small changes in how a payment is accepted may push it into a more expensive tier.
For businesses that process many card-not-present transactions, rewards cards, or higher-ticket sales, these hidden cost shifts can add up quickly.
Tiered Pricing vs. Interchange-Plus Pricing
Interchange-plus pricing is often considered the more transparent alternative. With interchange-plus, the merchant pays the actual interchange fee set by the card networks plus a clearly stated processor markup.
Here is the main difference:
- Tiered pricing: Transactions are grouped into broad categories, and the processor decides how to classify each sale.
- Interchange-plus: Transactions are billed at the actual interchange rate plus a fixed markup.
Interchange-plus usually provides better visibility into your real processing costs, making it easier to forecast expenses and compare merchant services providers. Tiered pricing, by contrast, can make it difficult to know whether you are paying a fair rate.
Who Tiered Pricing May Work For
Tiered pricing may work reasonably well for businesses with a high percentage of basic, card-present transactions and low risk of being downgraded into more expensive tiers. Examples may include small retail shops or service providers that mostly accept standard debit cards in person.
Even then, merchants should review statements carefully and ask detailed questions before signing a contract. A pricing model that looks affordable for one business could become expensive for another, depending on transaction mix and customer payment behavior.
Questions to Ask Before Choosing a Provider
If a processor offers tiered pricing, ask the right questions before committing:
- What transactions qualify for each tier?
- How often are transactions downgraded to a higher tier?
- Are there monthly minimums, statement fees, or PCI fees?
- Can I see sample statements from existing merchants?
- How does this compare to interchange-plus pricing for my business type?
These questions can help you understand not just the advertised rate, but the true cost of the merchant account.
How to Evaluate Your Current Pricing Structure
If you already use tiered pricing, review several recent statements and calculate your effective rate by dividing total processing fees by total card sales. This gives you a more realistic view of what you are actually paying.
Also look for patterns. Are most of your transactions being charged at mid-qualified or non-qualified rates? Are fees changing based on card type, entry method, or customer location? If so, your current pricing structure may be costing more than you realize.
Comparing quotes from multiple merchant services providers is also a smart move. Ask each provider to explain how their pricing model affects your specific transaction mix rather than focusing only on the lowest advertised rate.
Conclusion
Tiered pricing merchant services can be easy to understand on the surface, but the real cost is often less clear than it appears. While the model may suit some low-risk businesses, many merchants find that interchange-plus pricing offers better transparency and more predictable fees. Taking time to review your statements, ask direct questions, and compare alternatives can help you choose a payment processing solution that supports your bottom line.